Rates Went Up. So Did Everything Else.
- ATBS Staff

- Aug 28
- 6 min read
Capacity Not Demand… Why This Recovery is Different
For years, carriers were stuck in a brutal squeeze. Rates fell off their pandemic highs, freight demand softened, and operating costs climbed the entire time. The result was one of the hardest margin environments the industry has ever produced. Many carriers exited. The ones who survived did it by getting disciplined, and many of them still ran near break-even or worse while they did it.

Then the market turned. Rates climbed, and for the first time in a long while the headline numbers started to look like the good years again.
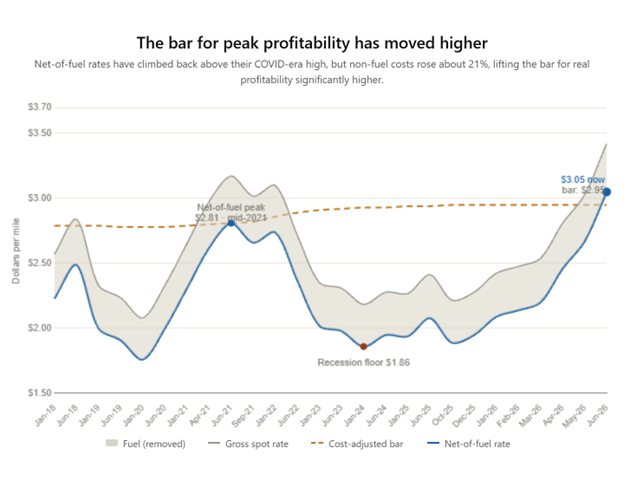
It would be easy to read that as a return to the freight boom. That reading misses the most important thing about it. The number on the load board and the profit in your pocket are not the same number, and the distance between them is wider now than it used to be. Rates recovered into a cost structure that also recovered, and the cost side moved first.
The Cost Base is Not What it Was
Nearly every major line item in a trucking operation costs more than it did at the last peak. Insurance, maintenance, equipment payments, and the long tail of non-fuel operating expenses have all moved up, and several of them have moved up significantly.
Part of that is straightforward inflation. Part of it is the downturn itself. When trucks run fewer miles, the same fixed costs get spread across fewer miles, which pushes cost per mile up even when the underlying bills hold steady. Two forces pointing the same direction. The driver feels both.
The practical consequence is simple. A rate that produced a healthy profit at the last market peak does not produce that same profit today. Rates have to clear a higher bar just to get you back to where you were, and gross rate comparisons across market cycles will lie to you unless you adjust for what it now costs to run the truck. That is why the honest measure of a recovery is not whether rates beat the last peak. It is whether they beat the last peak after the cost base is accounted for. By that measure, the recovery is real but far thinner than the headlines suggest.
This is a Capacity Recovery, Not a Demand Recovery
Freight demand did not come roaring back and pull rates up with it. Volumes have been unremarkable. What changed is the supply side. Capacity left the market and did not come back. Carriers failed or parked trucks during the downturn. Enforcement tightened on the illegal and non-compliant capacity that had been sitting underneath the market and suppressing rates for years. Equipment got older, financing got harder, and insurance underwriting got stricter for anyone trying to come in new.
That distinction matters because demand-driven booms and supply-driven ones behave differently. A demand-driven spike ends when demand normalizes, and it usually does so quickly. A supply-driven recovery ends when capacity comes back. So the real question for anyone trying to understand how long this lasts is not what the freight economy does next. It is how quickly new trucks and new drivers can enter the market.
Why the Capacity Side Looks Structural
Historically, high rates pulled drivers into their own authority, banks financed trucks, insurance was obtainable, and within a few quarters the capacity that rates had summoned showed up and competed those same rates back down. That reflex is what turned every previous upcycle into a short one.
The entry path is harder now, and it is harder in ways that do not reverse simply because rates improve.
First, getting into a truck costs more. Equipment, financing, and startup capital all demand more than they used to, and insurance for a new authority is harder and more expensive to get.
Second, the vetting has tightened. Regulatory and enforcement pressure on new and marginal operators is heavier than it has been in a long time, and the freight itself is harder to access. Brokers carry real liability exposure when a carrier they tendered a load to is involved in a crash, and the size of those judgments has made them conservative about who they use. A new authority with no safety score is a risk they have little reason to take. The practical effect is that a new entrant can have the truck, the authority, and the insurance and still struggle to get quality freight.
Third, the pipeline that produces new owner-operators stalled out. The path runs company driver, then owner-operator leased to a carrier, then their own authority, and it takes years to walk. Through the downturn it largely stopped running. Few company drivers stepped up, and plenty of owner-operators went the other direction and took a company seat back. That is what makes the timing structural rather than cyclical: even if conditions turned favorable today, the cohort that would normally be ready to go out on its own never took the first step.
Add those up and you get something previous cycles did not have: friction on the way in. Capacity can still return, but it returns slower, and the slower it returns the longer the rate environment holds. The mechanism that used to end every upcycle early is not gone, but it is impaired.
Freight is Still Nimble, and That is the Honest Caveat
Freight is one of the most adaptive markets there is. When truckload pricing rises, freight moves. Some of it goes to rail and intermodal. Some of it goes into private fleets, where large shippers pull volume in-house rather than pay the market. Some of it gets redesigned out of existence entirely through network changes, consolidation, denser loading, and shorter supply chains. That is not speculation. It is what shippers do every time truckload gets expensive.
That safety valve puts a ceiling on how far truckload rates can run before volume starts leaking to other modes. It does not, however, undo the floor. The cost of operating a truck is permanently higher, and carriers cannot run below cost indefinitely no matter what the demand picture looks like. A higher cost floor means a higher rate floor. Demand shifting to other modes changes how much room there is above that floor. It does not push the floor back down. So the reasonable expectation is not a runaway market. It is an elevated one, with real upward pressure as long as capacity stays constrained.
What This Means For You
The benefit is never evenly distributed. Equipment type, region, lane mix, debt structure, and operational discipline all decide who feels the upside and when. A market that has cleared the bar on average still leaves plenty of individual operators sitting below it. For anyone feeling the upside, this is the window to rebuild: restore margin, pay down debt, catch up the deferred maintenance. But discipline matters more now, not less, because a rising market can still evaporate for anyone who over-expands, chases bad freight, or lets costs drift. The market improving is not the same as your business improving.
That goes double if you are weighing your own authority. A strong rate environment feels like the green light you have been waiting for, but the case for a longer cycle is still a forecast, and a forecast is a poor foundation for a decision that loads you with fixed costs that do not go away when the market softens. Make that call on a plan that survives a bad year, not on the strength of a good one, and run an updated profit plan with your ATBS Business Consultant before you do.
That is the through line: know your numbers, and decide from those numbers instead of the emotion of the moment. It is what ATBS pushed through the downturn, and it matters just as much now, because a rising market is when it is easiest to stop paying attention. For owner-operators, now is the time to take stock of what worked over the last few years and what did not, and to turn those lessons into a plan built for the market you are actually operating in. What matters is not what happened. It is what you do with what you learned. That is the work we are built for: setting fleets up to grow, and putting owner-operators in the best position to reach their business and financial goals.